
Skip to content
Email: contactus@precisa.in
Phone number: +91 98450 76647
  • Products
    • Bank Statement Analysis
    • GSTR Analysis
    • Credit Report Analysis
    • Anti-Money Laundering (AML) Analysis
    • Account Aggregator Integration
    • DSA Service
    • Forensic Investigation
    • API Integration
  • Industries
    • NBFC
    • DSA
    • Govt. Departments
    • CA Firms
    • Forensic
    • Fintech
    • Enterprise
    • Advisory
    • International
    • TSP
    • Private Lender
  • Solutions
    • Use Cases
      • For CA and Tax Professionals
      • NRI Bank Statement Analysis
      • NBFCs & Fintech Companies
      • For Private Lenders
      • For Insurance Underwriting
      • Credit Bureau Report Analysis
      • GSTR Analysis Tool
      • ITR Analysis Tool
      • Fraud Detection
    • Supported Banks
      • All Supported Banks
      • Indian Banks
      • US Banks
      • Middle East Banks
      • Malaysian Banks
      • International Banks
      • European Banks
      • Canadian Banks
      • African Banks
      • Payment Banks
    • Blog
  • Clients
  • Pricing
  • Tools
    • ITR Analyser
    • GST Return Analyser
    • Credit Bureau Analyser
    • Bank Statement Analyser
  • Sign In
Try Now
Fintech

Can Co-lending Fulfill RBI’s Aim to Connect NBFCs, HFCs, and Banks?
February 7, 2022 Precisa Team No comments yet
Co-Lending-Fulfill-RBIs-Aim-to-Connect-NBFCs-HFCs-and-Banks

The pandemic has altered the cost of living for the average Indian. The Center for Monitoring Indian Economy revealed that 55% of households in India experienced a decrease in their incomes while only 3% of the households had an increase of the same.

Marko Carevic, Chief Marketing Officer of Home Credit India, said that nearly 67% of Indians are open to taking up loans and are shifting their behaviours from a loan-averse approach.

According to a study, the top reason for most people to take up loans is to fulfil family needs and wishes, while the second reason was to upgrade their lifestyle with the purchase of automobiles, household appliances, home or gold.

The Credit Information Company said that the loan market has potential avenues among the 40 crore people between 18-34 in the rural and semi-urban areas.

But, these segments have only seen an 8% loan penetration. Some others who fall under these segments are young entrepreneurs, farmers seeking funds for agriculture, MSMEs, etc., all of whom are vital for developing the Indian Economy.

All the data points out a barren lending scenario in a potential market. However, in recent years, the Reserve Bank of India is launching several initiatives to boost the nation’s lending sector. Co-Lending is one such effort. Let’s see how this effort can bridge the credit gap in India. Or if it could?

What is RBI’s Co-Lending Model?

RBI announced the Co-Lending Model (CLM) in November 2020 as an initiative to meet India’s unmet segments and offer loans to India’s priority sector. The CLM is said to be the christening of the RBIs Loan Scheme that was announced in September 2018.

CLM brings greater flexibility to lending institutions and helps ease the liquidity crisis for non-bank lenders by enhancing credit flow to productive sectors.

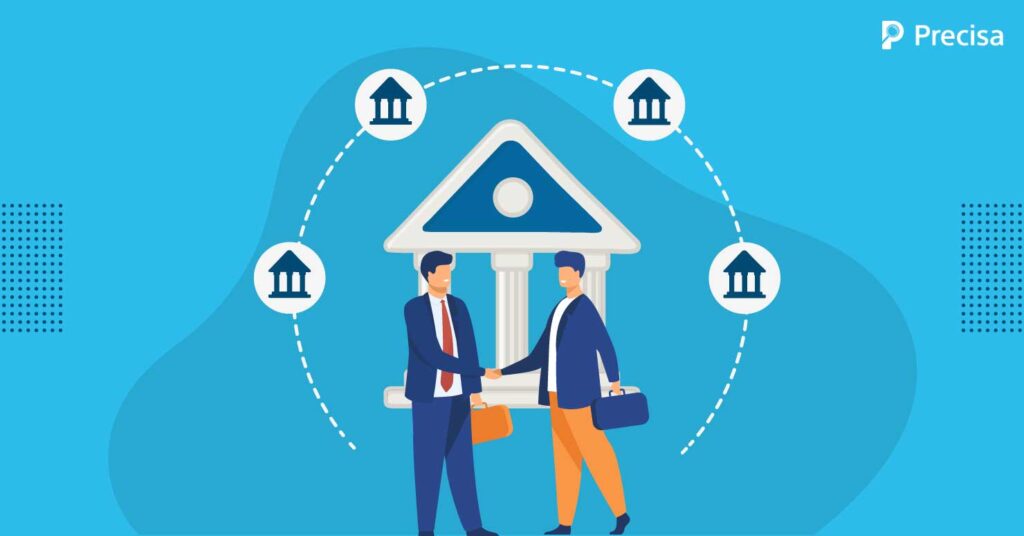
How CLM Connects banks and NBFCs and HFCs

The objective of the CLM was to create an easy credit flow to the unserved and the underserved sectors of the Indian economy.

The scheme makes the borrowers attain funds at an affordable cost. The Co-Lending Model uses NBFCs and HFCs since they have a greater reach to the masses, whereas the banks offer the funds to the ultimate borrower at a lower cost.

This is how the CLM works:

  • Lenders or customers go through the NBFCs to lend money from banks.
  • The borrower agrees with the NBFCs and the bank.
  • All the roles and responsibilities of each party are clearly defined.
  • Both the bank and the NFBCs become the lenders mutually decide on an interest rate for a particular loan.
  • An escrow account is used to make all transactions between the bank and the NFBCs. This eliminates any misplacement of funds.
  • As per the RBI guidelines, the NFBCs and the HFCs take care of the origination and collection of housing loans.
  • The banks leverage the majority of the loan.
  • This translates to 80% of the loan reflecting on the bank’s balance sheet, while 20% on the NBFCs or HFCs balance sheet.

In simple words, the banks lend to the NBFCs or the HFCs and lend to the ultimate borrower or the priority sectors.

Notable bank-NFBCs tie-ups

SBI, the largest lender in India with around 22,230 branches, signed with Adani Capital, a small NFBC with just 60 branches for co-lending to farmers. They dispersed around Rs. 1000 cr to help them buy tractors and farming equipment.

The Union Bank of India also signed a co-lending agreement with Capri Global Capital Ltd. to offer secured loans to MSMEs between Rs 10 lakhs to Rs 100 lakhs.

What are the Risks of Co-Lending?
What-are-the-risks-of-Co-Lending

As mentioned earlier, with the CLM, the banks have 80% of the risk of lending on their backs, while NFBCs only hold 20% of the share.

However, all the roles and responsibilities—including the features of the agreement—are laid out before the borrower. Moreover, since the lending takes place in accord with these points, the process becomes much more straightforward.

According to these roles and responsibilities, the NFBCs decide the borrower, and the banks fund most of the loan.

AI-powered fintech is making co-lending easy

Before deciding on a borrower, there is a lot of verification that has to be made. Therefore, making informed decisions and keeping the numbers and projections accurate is vital. This is why AI-powered platforms like Precisa can automate the decision-making process with real-time API.

Precisa can make your banking operations and lending decisions smoother, quicker, and more accurate. For more information, contact us at contactus@precisa.in

  • AI in Fintech
  • Digital Lending

Post navigation

Previous
Next

Leave a Reply Cancel reply

Your email address will not be published. Required fields are marked *

Search

Categories

  • Bank Statement Analysis (201)
  • Credit Appraisal (67)
  • Digital Lending (125)
  • Fintech (84)
  • Fraud & AML Detection (6)
  • NBFC Software (10)
  • Understanding Precisa (27)

Recent posts

  • Live vs Closed Loans
    Live vs Closed Loans: What a Credit Bureau Report Shows
  • Loan Processing Still Relies on Manual Work
    Why NBFC Loan Processing Still Relies on Manual Work
  • Best GST Analysis APIs in India (2026): 7 Options for Lenders Compared
    Best GST Analysis APIs in India (2026): 7 Options for Lenders Compared

Tags

Account Aggreagtor AI in Fintech AML compliance API To Get Bank Transactions Automated Bank Statement Analysis Bank Accounts Bank Financial Statement Analysis Bank Statement Analysis Bank Statement Analysis API Bank Statement Analysis Tools Bank Statement Fraud Detection BNPL Co-Lending credit analysis Credit Appraisal Credit Appraisal Software Tools Credit Assessment Credit Bureau Data Quality and Integrity Digital Lending Due Diligence early warning signals Embedded Finance Financial Data Analysis Tools Financial Inclusion Financial Industry Financial Security Financial Statement Analysis Software Fintech Fintech Companies fraud detection Fraud Investigation GST analysis API GSTR GSTR Analyser ITR Analysis Lenders Loan Management System Money Laundering MSME NBFC NBFC lending Open Banking Precisa RBI

Continue reading

Mismatches Between GSTR-2B and GSTR-3B - Feature Image
Fintech

How to Reconcile ITC Mismatches Between GSTR-2B and GSTR-3B

September 2, 2026 Soma Sharma No comments yet

Every month, thousands of businesses claim input tax credit in GSTR-3B that does not fully match GSTR-2B. Sometimes it is a vendor who filed late. Sometimes it is an invoice booked in the wrong period. Either way, the GST system now catches the gap on its own, and it does not wait for an audit […]

Verify a GSTIN Online
Bank Statement Analysis

How to Verify a GSTIN Online Before Approving a Business Loan

May 15, 2026 Soma Sharma No comments yet

Business loans involve a basic question that sounds straightforward: is this a real, operating business? At Precisa, it’s a question that runs through thousands of loan files we process for lenders and NBFCs across India. GSTIN verification is one of the fastest ways to answer it, and one of the most skipped steps in informal […]

AI Bank Statement Fraud
Bank Statement Analysis

AI-Generated Bank Statement Fraud: Statement Analysis Defences for Lenders

March 27, 2026 Santosh Shetty No comments yet

Bank statement fraud isn’t new. Borrowers have been altering statements for years, using basic editing tools to change balances, erase bounced cheques, or inflate salary figures. What’s changed is the sophistication of those tools and the effort required to produce something convincing. AI can now generate bank statements that pass a visual inspection without raising […]

Mumbai

403, Mayuresh Chambers, 4th Floor, Sector 11, CBD Belapur, Navi Mumbai, Maharashtra - 400614

📍Locate us

Pune

Rachana Park, 3rd Floor, Atreya Society,
Off. Senapati Bapat Marg, Wadarvadi, Pune,
Maharashtra - 411016

Bengaluru

WeWork, Cabin No 02126, 2nd Floor, Vaishnavi Signature,
No. 78/9, Outer Ring Road, Bellandur Village, Varthur Hobli,
Bengaluru East, Karnataka - 560103

Links
  • About
  • Cancellation Policy
  • Terms Of Use
  • Privacy Policy
Tools
  • ITR Analyser
  • GST Return Analyser
  • Credit Bureau Analyser
  • Bank Statement Analyser
Subscribe to our newsletter

Sign up for our weekly newsletter to get the latest news, updates & amazing offers delivered directly in your inbox.


    © All Rights Reserved • Precisa | A Product of Finezza Information Technologies Pvt. Ltd • MADE WITH ❤️ & ⚡ IN INDIA.