
Can Co-Lending Be the Saviour Indian NBFCs Are Hoping For?
India’s credit gap widened in tandem with the economy’s unprecedented growth. In such a market condition, debt financing can be of some help, if not for the straining procedures, collateral demands, and heavy paperwork.
As banks fell short of presenting a favourable image to businesses, NBFCs became the obvious choice for credits. In all this, co-lending can enhance the credit flow for the better.
How can co-lending be the saviour that NBFCs in India hoped for? Continue reading to learn more about co-lending and how it can salvage NBFCs from the vices.
What is Co-Lending?
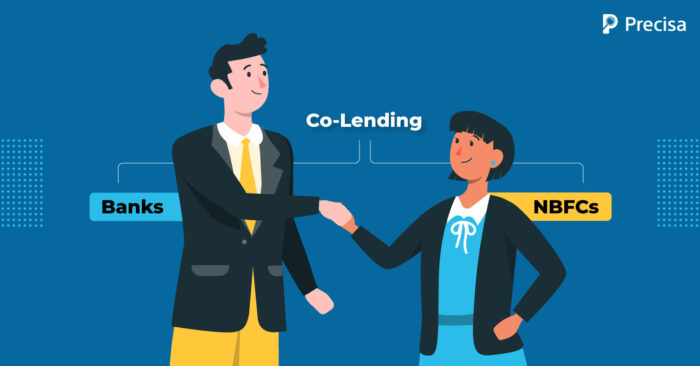
Co-lending attempts to bridge the gap between banks and non-bank finance companies, ultimately increasing the flow of credit into the economy.
A co-lending arrangement is when two parties, for example, banks and NBFCs collaborate to lend/finance customers. Banks primarily focus on capital and trustworthiness, while NBFCs concentrate on customer service, innovative products, fast paperwork, seamless data integration, and reaching every corner of the country.
Can Co-Lending be the Saviour that NBFCs in India Hoped For?
Weighing the realistic scenarios in our previous blogs, although the model was intended to address NBFC challenges, it was more of a vehicle by which the big banks could reach out to the small businesses.
However, the fact remains that NBFCs benefit from all of the above. How? Keep reading:
Technology to empower the credit market
Banks have historically faced higher costs, more paperwork, and a lack of regional connections. Despite these challenges, co-lending offers banks a fresh start.
Starting with digital lending, AI-assisted underwriting, e-documentation, enhanced KYC, auto accounting, and more, co-lending, through NBFCs, aims to transform the way credit is provided in India.
Technology is changing the face of customer management by leveraging data and analytics. As a result, we will see a dramatic digitalisation of the industry, accelerated by co-lending protocols post-pandemic.
Infusing capital
India’s capital markets provide a fascinating narrative. India cannot rely on debt markets to bridge its credit gap, considering the lack of participation and conservative policies.
Banking then becomes the focus. Look no further than banks for liquidity. Indian banks could potentially fund a few economies around the world. However, the economy’s liquidity could never reach its frontiers with many issues, be it social, political, or anything else.
Luckily, co-lending bridges this gap – combining credit from both sides. Profiting from the bank’s brand image, connections, and credit limit, NBFCs solve the credit gap with demographic knowledge.
Many tech-first companies bring onboard AI and financial technology to offer the best lending models and continuous financial innovation.
Shares profits and risks
Banks deal with the most significant hit when loans turn sour. The RBI guidelines allow NBFCs to decide everything related to loans. However, the co-lending model is beneficial for both the NBFCs and the banks.
Neither party’s balance sheet suffers, and risk management takes centre stage. A well-managed risk will yield more profits as the default risk is diluted.
Maintaining sustainability
A double underwriting system, government-managed risk, and barely any corruption have demonstrated that lending institutions can work together and solve India’s most significant development challenge — access to credit and financial infrastructure.
Co-lending has fulfilled the need for India’s two largest credit providers, the Banks and NBFCs, to work together. This offers the lending industry a level of stability never before seen.
We need to shift our debate from ‘banks vs NBFC’ rather ‘banks and NBFC vs traditional financing’ as it positively steers the country’s credit market.
Emphasising MSMEs
Despite being highly informal, MSMEs contribute to 30% of India’s GDP, fostering entrepreneurship. Nonetheless, credit is a significant hurdle for MSMEs.
The banking industry has a reputation for favouring larger corporations over small businesses despite a dearth of financing. While banks are not to blame, too, as most MSMEs and SMEs lack credit histories.
But co-lending can change this for the MSME sector technology and digitalisation. As discussed above, many processes can change for good, time focused, and advanced.
This will probably stimulate the dwindling credit market, providing credit to eligible MSMEs turned away due to poor credit histories.
By partnering with NBFCs and fintechs, credit juggernaut banks can increase liquidity and lending several times over. In addition, to ease the credit gap in the country, companies are taking advantage of revenue-based lending and embedded finance solutions.
Where Are We Headed To?
It is too early to predict how competitive co-lending will be in India, as it resides in its infancy. Banks and NBFCs are both strong players in co-lending, but critics say their weaknesses lead to their loss of appeal. Nevertheless, the pandemic has added a new wrinkle to the story of lenders.
Digitalisation is becoming more relevant than ever, and co-lending has the potential to change traditional banking forever. However, only time can answer these assumptions.
Need more insightful information regarding co-lending? Precisa can help you with all things lending. Contact us today!


