
Lender Awareness: Understanding the Most Common Business Loan Frauds and Scams
Many lenders often decide to entice borrowers with the promise of instant loans. However, lenders’ urgency to disburse more loans and borrowers’ eagerness to receive them can have adverse consequences, especially if the former does not perform due diligence.
For example, lenders face the risk of engaging in loan fraud when dealing with dubious borrowers.
In 2023, for instance, the CBI filed a loan fraud case worth INR 80 crores against a business borrower who allegedly manipulated the books and financial statements to inflate sales, income, and profit.
On the other hand, lenders may be tempted to take shortcuts when accelerating growth, which can lead to hasty and inaccurate underwriting decisions.
Moreover, in several cases, bad players have indulged in loan scams, thus lowering customer trust, especially in newer digital lending platforms.
In this blog, we identify various business loan frauds and scams and how lenders can strengthen risk assessment and address issues proactively.
What Are Business Loan Frauds and Scams?
Business loan frauds refer to a set of practices adopted by borrowers geared towards inflating their creditworthiness in the underwriting process, to secure a business from a lender.
On the other hand, scams are practices run by fraudulent businesses impersonating lenders to scam borrowers for their money.
Lenders run the risk of offering loans to fraudulent borrowers due to a lack of strong risk assessment and fraud detection capabilities. This is where technology can play a role in supporting businesses to scale sustainably and profitably.
However, let’s first understand the various types of business loan frauds and scams impacting the lending landscape.
Common Business Loan Frauds and Scams
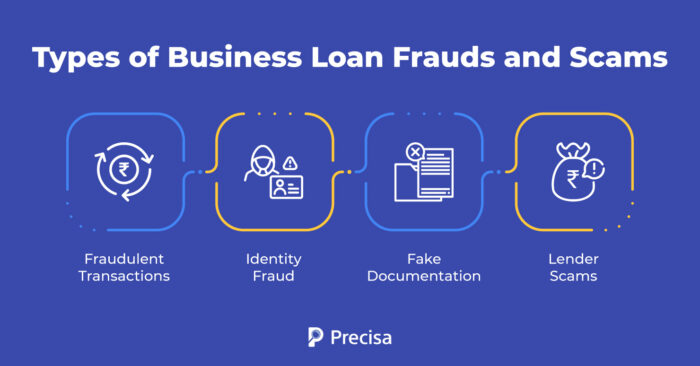
Here’s a brief look at common business loan frauds and scams lenders must be aware of:
1. Fraudulent Transactions
Sometimes, businesses execute certain types of transistor fractions to demonstrate they are generating revenues and average in cash flows.
For instance, a company may execute circular transactions, a scenario where it sells products to another company and purchases them back. Hence, no revenue or profit is generated. The companies may have shared ownership or have reached an agreement.
At times, multiple companies are involved. Hence, it is challenging for lenders to recognise such transactions.
2. Cases of Identity Fraud
At times, a borrower may impersonate another individual without authorisation. Usually, they will impersonate someone with a good credit score, positive cash flow in their bank statements, and a similar-sounding name. The person being impersonated may even be deceased.
As lenders scale their businesses, verifying identities becomes more challenging without access to supportive technology.
3. Cases of Fake Documentation
In some cases, borrowers may slip in fraudulent documents to help enhance their creditworthiness. For instance, they may fabricate Bank documents, signatures, and papers demonstrating ownership of assets.
These documents may display inflated revenues and profitability, interfering with accurate underwriting processes. It can be challenging to identify fake documentation, especially if it is presented with authentic documents.
4. Lender Scams
While borrowers may engage in fraudulent activities to secure a loan, there are growing incidents of fraudsters impersonating lenders to scam borrowers.
Such players may demand upfront registration fees, offer instant loans with exceedingly high interest rates, demand unconventional payment methods, and offer incomplete documentation.
They may vanish once a borrower makes an upfront payment or pressures potential borrowers into a vulnerable financial position to take an instant loan that will prove expensive in the long term.
Such incidents reduce borrower trust, and while there is not much lenders can do about such cases, it helps to stay aware and introduce processes and systems that raise customer trust.
Impact of Business Loan Frauds
When lenders fall prey to business loan frauds and scams, they are impacted in several ways:
- Rising cases of business loan fraud contribute to the growth of non-performing assets, which eat into the lender’s profitability. This is because lenders invest significant time and financial resources in the loan application and disbursal process.
- Lenders will need to invest resources in the investigation of such fraudulent borrowers. This approach comes at a significant cost.
- Lenders themselves may come under the radar of investigative agencies.
- Lenders may need to pay certain penalties and fines if they do not comply with all the requirements of the Reserve Bank of India (RBI) requirements.
- Too many cases of loan fraud can also impact the credibility of Orlando, which can raise concerns with existing and potential borrowers, which is bad for business.
- If the ticket size of loan fraud gets too high, the lender may also need to shut down operations as running the business becomes unsustainable.
How to Avoid Common Business Loan Frauds
As this business attempts to scale, it becomes important for them to consider investing in technology that provides a holistic solution to the problem. As mentioned above, accelerated growth at the risk of inaccurate underwriting can lead to various consequences.
By leveraging an automated, AI-powered and cloud-based financial analysis solution, lenders can strengthen risk management as well as fraud detection capabilities.
- It transforms the entire underwriting process end-to-end, leveraging AI, which can recognise irregular transaction patterns and minute distinguishing characteristics in fake documentation.
- These tools can also do thorough cross-checks around borrower identity to nip potential identity theft in the bud.
- Another benefit of such software is that it comes with the ability to cross-check revenues by cross-referencing revenue-related transactions with data pulled from a company’s account on the Goods & Services Tax Returns (GSTR) from the GST portal.This approach helps establish the authenticity of cash flows, especially among smaller businesses that lack a credit history.
The Takeaway
Lenders can strengthen their risk assessment and fraud detection capabilities by leveraging superior financial analysis software. They can reduce the potential for business loan fraud.
The state-of-the-art technology enables lenders to run streamlined, efficient, and accurate underwriting operations, paving the way to build a profitable, sustainable business.
This is where Precisa’s advanced algorithms can help comprehensively detect potential loan fraud within minutes.
Presica’s comprehensive and seamless financial data analysis solution simplifies and speeds up the process through automation. The software provides actionable insights on a customisable dashboard, thus helping companies make informed business decisions.
Request a free demo today!


